Altria Narrows 2026 Guidance Range
August 29, 2026
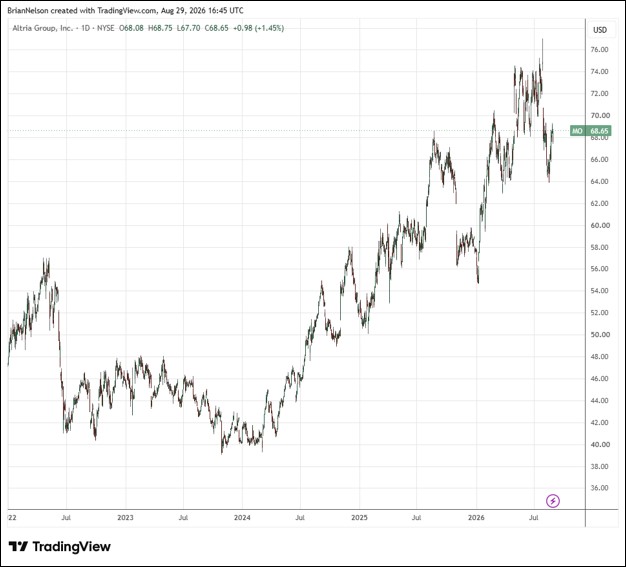
Image Source: TradingView By Brian Nelson, CFA Altria (MO) recently reported decent second quarter results with revenue and non-GAAP earnings per share coming roughly in-line with consensus expectations. Revenue net of excise taxes increased 1.2% year-over-year in the quarter, while adjusted diluted earnings per share advanced 2.8% from the last year’s period. Management had the following to say about the results: In the second quarter, our operating companies continued to deliver against the priorities we outlined at the start of the year – advancing our smoke-free portfolio, strengthening our traditional tobacco businesses and delivering significant returns to shareholders. In smoke-free, Helix expanded on! PLUS to 120,000 stores nationwide, engaged in trial-generating activities and prepared for additional line extensions to come
Dick’s Sporting Goods Faces Challenging Conditions in Athletic Footwear
August 29, 2026
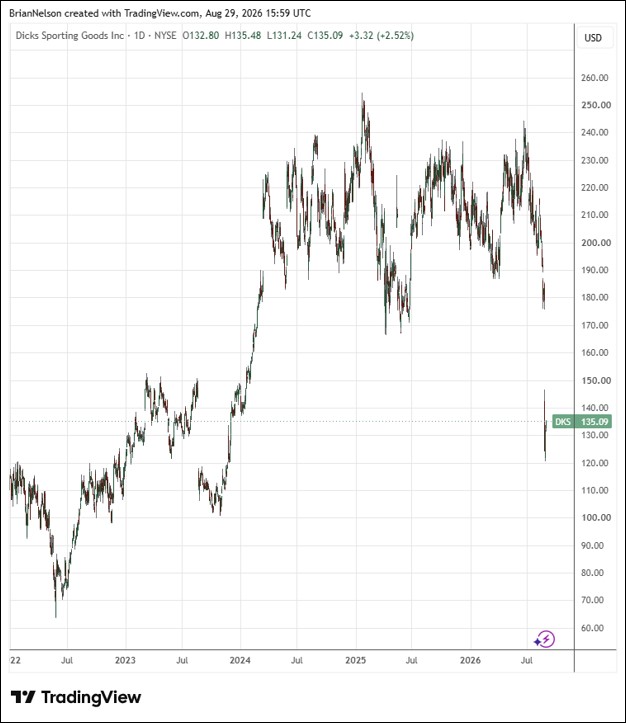
Image Source: TradingView By Brian Nelson, CFA Dick’s Sporting Goods (DKS) reported second quarter results August 25 that missed the consensus mark for revenue and non-GAAP earnings per share. Though DICK’S Business delivered 4.9% comp sales growth thanks to “broad-based growth across categories, including strong results from the 2026 FIFA World Cup, and growth in average ticket and transactions,” non-GAAP earnings per diluted share fell to $3.53 in the quarter from $4.38 in the prior year quarter (consensus was $3.76). Management had the following to say about the results: The DICK’S Business delivered a strong second quarter with broad-based growth across categories. As the quarter progressed, conditions across portions of the athletic footwear and apparel marketplace became increasingly promotional, and
Enterprise Products Partners Puts Up Record Second Quarter
August 1, 2026

Image Source: TradingView By Brian Nelson, CFA On July 30, Enterprise Products Partners (EPD) reported better than expected second quarter results with revenue and GAAP earnings per share exceeding the consensus forecast. Net income attributable to common unitholders was a record $1.8 billion, or $0.84 per diluted common unit, up 28%. Adjusted EBITDA hit a record high as well, coming in at $2.8 billion, up 17%. Operational DCF was a record $2.3 billion, which covered distributions declared by 1.9x. Adjusted CFFO was a record $2.5 billion, up 19%. Management had the following to say about the results: Enterprise reported strong volumes, earnings and cash flow for the second quarter of 2026. The partnership handled record pipeline and marine terminal volumes
Microsoft Puts Up Stellar Fiscal Fourth Quarter Results
August 1, 2026

Image Source: TradingView By Brian Nelson, CFA On July 29, Microsoft (MSFT) put up better than expected fourth-quarter fiscal 2026 results, with both revenue and non-GAAP diluted earnings per share exceeding the consensus forecast. Revenue of $90 billion increased 18% (up 17% in constant currency), while operating income of $40.6 billion advanced 18%. Non-GAAP net income was $35.3 billion, increasing 22%, while non-GAAP diluted earnings per share increased 23% in the quarter. Azure and other cloud services revenue increased 43% in the quarter, better than consensus expectations. Management had the following to say about the results: We are advancing the frontier on the cost-to-outcome curve, ensuring every customer can turn tokens into business results. This year, Azure revenue surpassed $100
Tesla’s Margins Squeezed; Free Cash Flow Negative in Q2
July 24, 2026

Image Source: TradingView By Brian Nelson, CFA On July 22, Tesla (TSLA) reported mixed second quarter results, with revenue exceeding the consensus forecast but non-GAAP earnings per share coming in below expectations. Total revenues increased 26%, while gross profit expanded 23%, as gross margins contracted 41 basis points from the same period a year ago. Income from operations fell 57% year-over-year, as its operating margin contracted 269 basis points, to 1.4%. Adjusted EBITDA fell 4% year-over-year, as adjusted EBITDA margins shrunk 353 basis points, to 11.6%. In the quarter, non-GAAP net income and non-GAAP earnings per share fell 17% and 18%, respectively. Management summarized the results as follows: Q2 was a strong quarter for our core vehicle, energy and services
Alphabet’s Free Cash Flow Goes Negative in Q2
July 24, 2026

Image Source: Alphabet By Brian Nelson, CFA On July 22, Alphabet (GOOG) (GOOGL) reported mixed second quarter results, but the strong performance was overshadowed by concerns over the return on the level of spending on artificial intelligence. Consolidated Alphabet revenues increased 24%, or 23% in constant currency, marking the 12th consecutive quarter of double-digit revenue growth. Google Services revenue increased 15% thanks in part to 17% growth in Google Search & other, while Google Cloud revenues increased a whopping 82%. Consolidated Alphabet operating income increased 30%, as its operating margin expanded 2 percentage points, to 34%. Management had the following to say about the results: Our AI investments are redefining what’s possible across every part of our business. Q2 was
Oracle Growing Fast, But Net Debt and Capital Spending Are Problematic
June 24, 2026
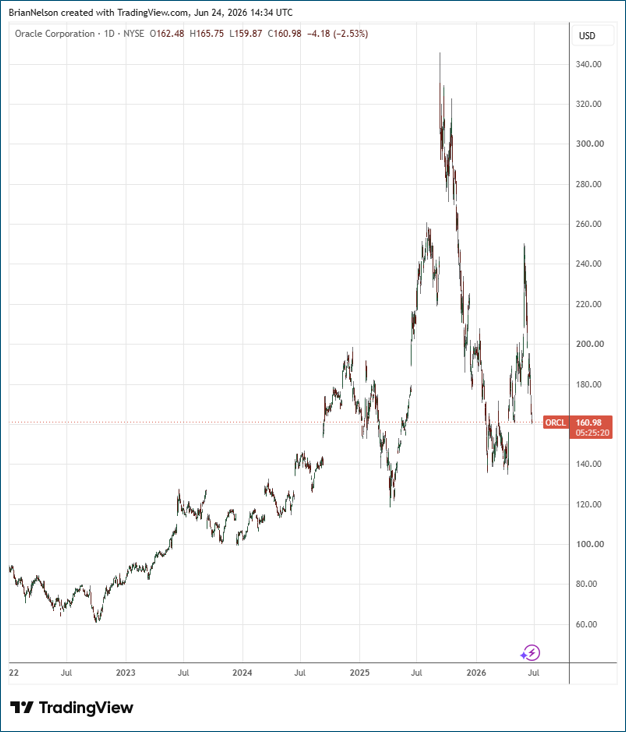
Image Source: TradingView By Brian Nelson, CFA Oracle (ORCL) recently reported fourth quarter fiscal 2026 results where both revenue and non-GAAP earnings per share came in better than expectations. The company set a number of new records in the quarter: record total revenue of $19.2 billion, up 21% in USD and better than consensus of $19.09 billion; record total cloud revenue of $9.9 billion, up 47% in USD, record non-GAAP earnings per share of $2.11, up 24% in USD and better than the $1.97 consensus mark; and record remaining performance obligations of $638 billion, up $85 billion sequentially. Management included the following in the press release: The large increases in Oracle’s RPO and revenue are driven by the growing demand
NextEra Energy and Dominion Energy to Combine
June 14, 2026

Image Source: TradingView By Brian Nelson, CFA NextEra Energy (NEE) announced on April 23 mixed first quarter results that showed a beat on the bottom line, but a miss on the top line relative to expectations. The results would soon be overshadowed by its deal with Dominion Energy (D), announced a few weeks later. Still, on an adjusted basis, NextEra Energy’s first quarter earnings were solid, coming in at $2.275 billion, or $1.09 per share, compared to $2.038 billion or $0.99 per share in the first quarter of 2025. Management had the following to say about the first quarter results: NextEra Energy is off to a terrific start for the year, delivering strong first-quarter results, with adjusted earnings per share
Amazon’s AWS Puts Up Fastest Growth in 15 Quarters
June 14, 2026
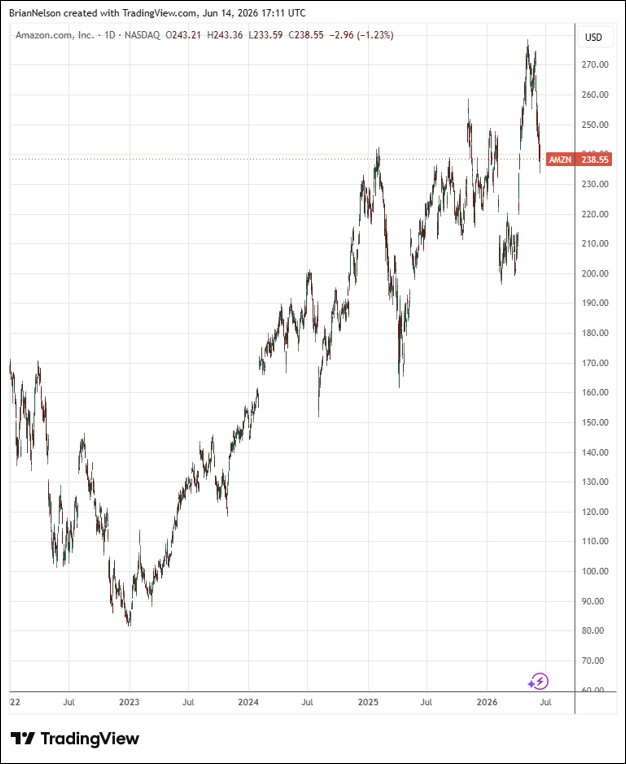
Image Source: TradingView By Brian Nelson, CFA Amazon (AMZN) recently reported first quarter results that beat consensus estimates on both the top and bottom lines. Adjusted net sales advanced 15% in the first quarter compared to the first quarter of 2025. North America segment sales increased 12% year-over-year, while international sales increased 19% year-over-year (11% excluding foreign exchange rates). AWS segment sales increased 28% year-over-year, beating the consensus forecast. Amazon’s operating income increased to $23.9 billion in the first quarter compared to $18.4 billion in the first quarter of 2025 and consensus of $20.8 billion. North America segment operating income was $8.3 billion, compared to $5.8 billion in the first quarter of 2025. International segment operating income was $1.4 billion,
Chipotle’s Transaction Growth Returns to Positive in First Quarter
June 14, 2026
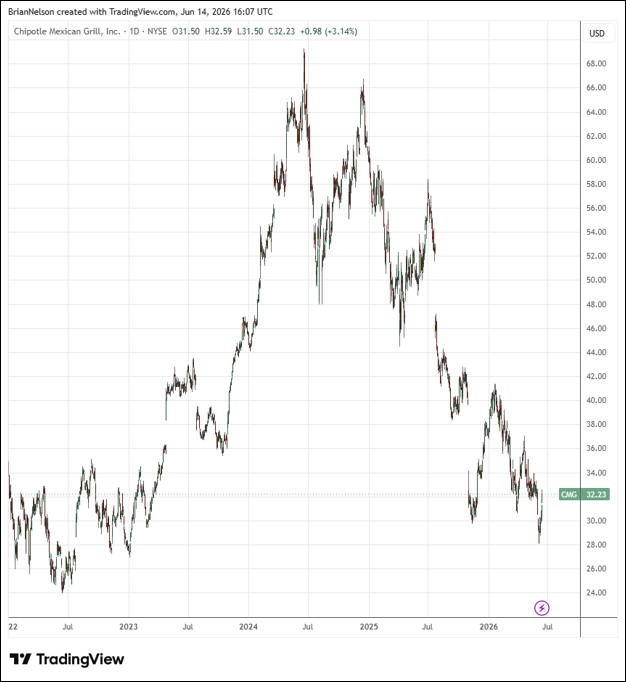
Image Source: TradingView By Brian Nelson, CFA Chipotle (CMG) recently reported first-quarter 2026 results that were mixed. The company beat expectations on the top line, but non-GAAP earnings per share came in in-line with expectations. Total revenue increased 7.4%, to $3.1 billion, thanks to new restaurant openings and, to a lesser extent, comparable restaurant sales growth of 0.5%, better than the consensus estimate calling for a decline of 0.9%. In the quarter, Chipotle benefited from higher transactions of 0.6%, which was offset in part by a 0.1% decline in average check. Margins faced pressure in the quarter due to inflation in beef and freight, higher produce usage, and increased labor costs. Adjusted net income for the first quarter of 2026
