Image Source: TradingView
By Brian Nelson, CFA
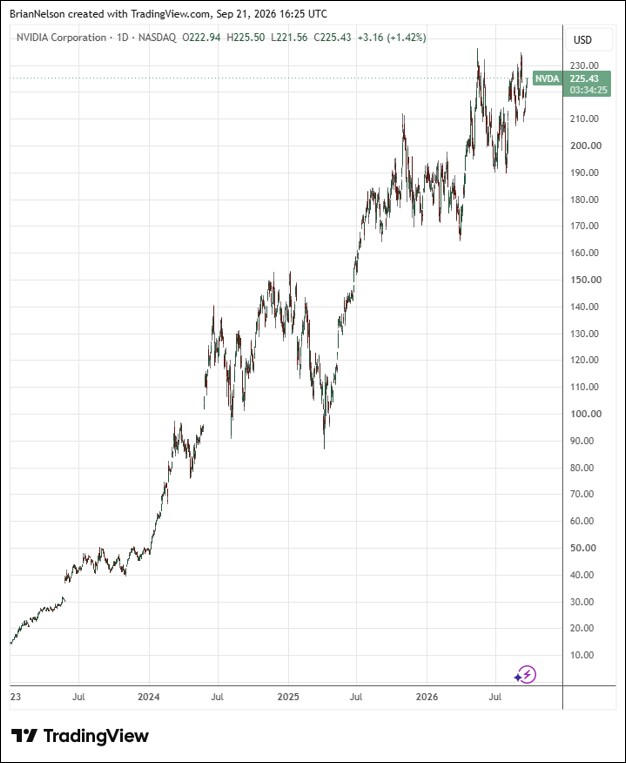
Nvidia (NVDA) recently announced better-than-expected second quarter fiscal 2027 results, with revenue up 106% from a year ago, and Data Center revenue up 117%, to $89 billion, from a year ago. The consensus estimate for Data Center revenue was $85 billion. For the quarter, on a GAAP basis, its gross margin advanced 2.6 percentage points on a year-over-year basis, while operating income expanded 124% from the same period last year. GAAP net income jumped 126%, while diluted earnings per share catapulted 128% higher, to $2.46.
CEO Jensen Huang had the following to say about the quarter:
AI has reached its inflection point. It’s doing useful work. Its tokens are productive and profitable. Now, compute is revenue. And demand is accelerating. This time last year, one lab alone was driving the buildout; today, we have a golden age of new AI labs and startups, multiple frontier labs scaling in parallel, a thriving open-model ecosystem and physical AI coming online — with strong momentum across the U.S. and around the world. The AI infrastructure buildout is at full steam. Vera Rubin, now in full production, was built to power exactly this moment.
Nvidia returned roughly $26 billion to shareholders in the form of buybacks and cash dividends during the second quarter of fiscal 2027, and it has approximately $99 billion remaining under its share repurchase authorization. Looking to the third quarter of fiscal 2027, management expects revenue to be $108 billion, plus or minus 2%, and the executive team is not assuming any Data Center compute revenue from China in its outlook. The consensus estimate called for $104.9 billion in revenue. GAAP and non-GAAP gross margins are expected to be 74%, plus or minus 50 basis points.
Nvidia ended the quarter with $99.4 billion in cash and marketable securities against $33.4 billion in short- and long-term debt. During the three months ended July 26, free cash flow was $21.4 billion. Looking to all of fiscal 2028, management expects revenue to grow approximately 70% year-over-year in what the executive team described as a “supply-constrained outlook.” Demand implies much higher growth, according to management. The average analyst estimate for revenue growth in fiscal 2028 was just 44%. We liked Nvidia’s outlook and still believe the company is a great fit for inclusion to the Best Ideas Newsletter portfolio.
—–
Brian Nelson owns shares in SPY, SCHG, QQQ, QQQM, DIA, VOT, RSP, and IWM. Valuentum owns SPY, SCHG, QQQ, QQQM, VOO, and DIA. Brian Nelson’s household owns shares in HON, DIS, HAS, NKE, DIA, RSP, SCHG, QQQ, QQQM, and VOO. Some of the other securities written about in this article may be included in Valuentum’s simulated newsletter portfolios. Contact Valuentum for more information about its editorial policies.
Valuentum members have access to our 16-page stock reports, Valuentum Buying Index ratings, Dividend Cushion ratios, fair value estimates and ranges, dividend reports and more. Not a member? Subscribe today. The first 14 days are free.