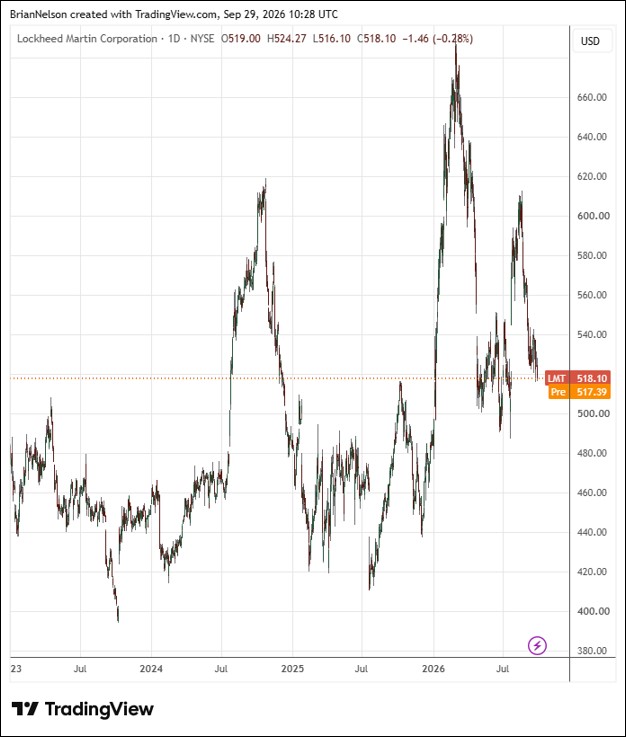
Image Source: TradingView
By Brian Nelson, CFA
Lockheed Martin (LMT) recently reported second quarter results that beat expectations on both the top and bottom lines. Sales increased 11%, to $20.1 billion, while the company generated net earnings of $1.8 billion, or $7.94 per share. Cash flow from operations was $3.2 billion in the second quarter compared to $201 million in last year’s quarter, while the company hauled in free cash flow of $2.9 billion versus a free cash flow burn in the second quarter of 2025.
Management had the following to say about the quarter:
We delivered strong second‑quarter performance, with over $20 billion in sales – a year‑over‑year increase of 11% – free cash flow of $2.9 billion, and $65 billion of new orders, which takes our backlog to a record $230 billion. This continued performance reflects more than just increased customer demand – it is evidence that our 21st Century Security® strategy, and its focus on integration, partnerships and operational excellence is working, resulting in increased business, and advancing the security needs of our nation and allies. We are delivering on our strategy, achieving a higher trajectory for our business and giving us confidence to raise our full year financial guidance. We now anticipate accelerated year‑over‑year sales growth of approximately 8%, driving 28% higher segment operating profit, and increased free cash flow, now projected to be over $7 billion.
These results are powered by consistent performance on the commitments we’ve made and by our investments to support the missions our customers will face next. Over the quarter, we took a major step forward in transforming munitions production, putting the framework agreements we announced earlier this year into action by signing a $35 billion multi-year contract with the Missile Defense Agency for THAAD. We continue to innovate at the speed our customers’ missions demand, taking our Sanctum counter-drone system from concept to successful live fire testing in just 45 days by combining a battle manager, radar, launcher, and combat-proven missile into one engagement chain. And, we are investing strategically to strengthen global defense manufacturing capabilities through our collaboration with General Motors Defense in the U.S. and our agreement with Rheinmetall to co-produce ATACMS in Europe.
Lockheed Martin is sitting on a record backlog of $230 billion, inclusive of the multi-year contract to produce THAAD interceptors. Looking to all of 2026, management now expects sales to be in the range of $79.75-$81.75 billion, up from the prior range of $77.5-$80 billion. Business segment operating profit for the year is now targeted in the range of $8.5-$8.7 billion, up from prior guidance of $8.425-$8.675 billion. Diluted earnings per share is now expected in the range of $29.95-$30.65, up from $29.35-$30.25 per share previously. Cash flow from operations for the year is now expected in the range of $9.2-$9.4 billion, narrowed from $9.15-$9.45 billion, while free cash flow is now expected in the range of $7-$7.2 billion, up from $6.5-$6.8 billion previously. We like the momentum behind Lockheed Martin’s business, and the company remains a holding in the Dividend Growth Newsletter portfolio. Shares yield 2.7% at the time of this writing.
—–
Brian Nelson owns shares in SPY, SCHG, QQQ, QQQM, DIA, VOT, RSP, and IWM. Valuentum owns SPY, SCHG, QQQ, QQQM, VOO, and DIA. Brian Nelson’s household owns shares in HON, DIS, HAS, NKE, DIA, RSP, SCHG, QQQ, QQQM, and VOO. Some of the other securities written about in this article may be included in Valuentum’s simulated newsletter portfolios. Contact Valuentum for more information about its editorial policies.
Valuentum members have access to our 16-page stock reports, Valuentum Buying Index ratings, Dividend Cushion ratios, fair value estimates and ranges, dividend reports and more. Not a member? Subscribe today. The first 14 days are free.