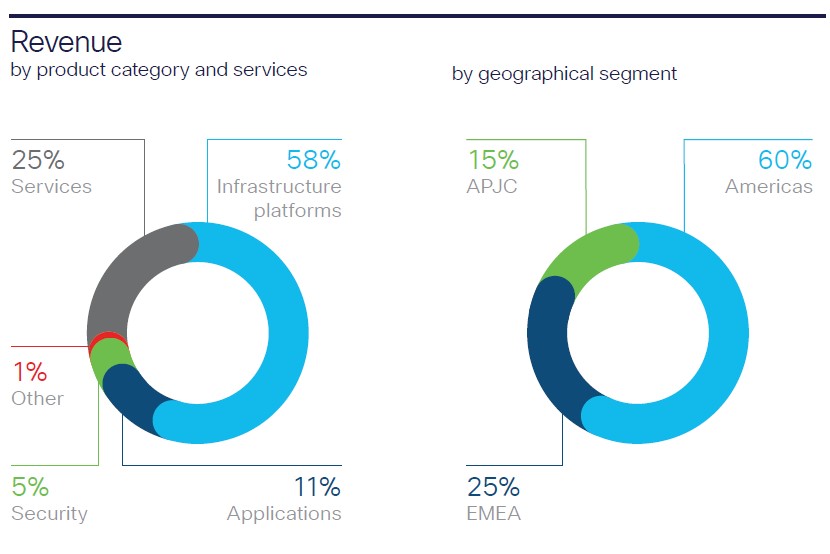
Image Shown: A breakdown of Cisco Systems Inc’s revenue as of the end of its fiscal 2019. Image Source: Cisco Systems – Fiscal 2019 Annual Report
By Callum Turcan
On November 13, Cisco Systems (CSCO) reported first quarter earnings for its fiscal 2020 (period ended October 26, 2019) that saw shares of CSCO sell off on November 14. That was likely due to the weak guidance management put out for the second quarter of the firm’s fiscal 2020, but we continue to like Cisco’s quality free cash flows and net cash balance.
Cisco’s GAAP revenues came in at $13.2 billion last quarter, up 1% year-over-year, and that growth rate rises to 2% when excluding sales related to the divestiture of Cisco’s Service Provider Video Software Solutions (‘SPVSS’) business in the second quarter of fiscal 2019 (divested on October 28, 2018). Near-term headwinds aside, we continue to like the company in both our Best Ideas Newsletter and Dividend Growth Newsletter portfolios. Shares of CSCO yield a nice ~3.1% as of this writing, and trade meaningful below our fair value estimate of $56 per share.
Guidance and Non-GAAP Gross Margins
Management sees Cisco’s revenues declining by 3%-5% year-over-year in the second quarter of fiscal 2020 due in part to exogenous headwinds pressuring the firm’s core businesses. In particular, sales generated from Cisco’s ‘Infrastructure Platforms’ segment are coming under fire, down 1% year-over-year last quarter (on both an adjusted and unadjusted basis).
On a non-GAAP basis, Cisco’s total gross margin came in at 65.9% in the first quarter of fiscal 2020, up from 64.2% in the same period a year ago (a year-over-year increase of ~170 basis points). That was due to rising non-GAAP ‘Product’ gross margins (up ~250 basis points year-over-year) offsetting declining non-GAAP ‘Service’ gross margins (down ~40 basis points year-over-year).
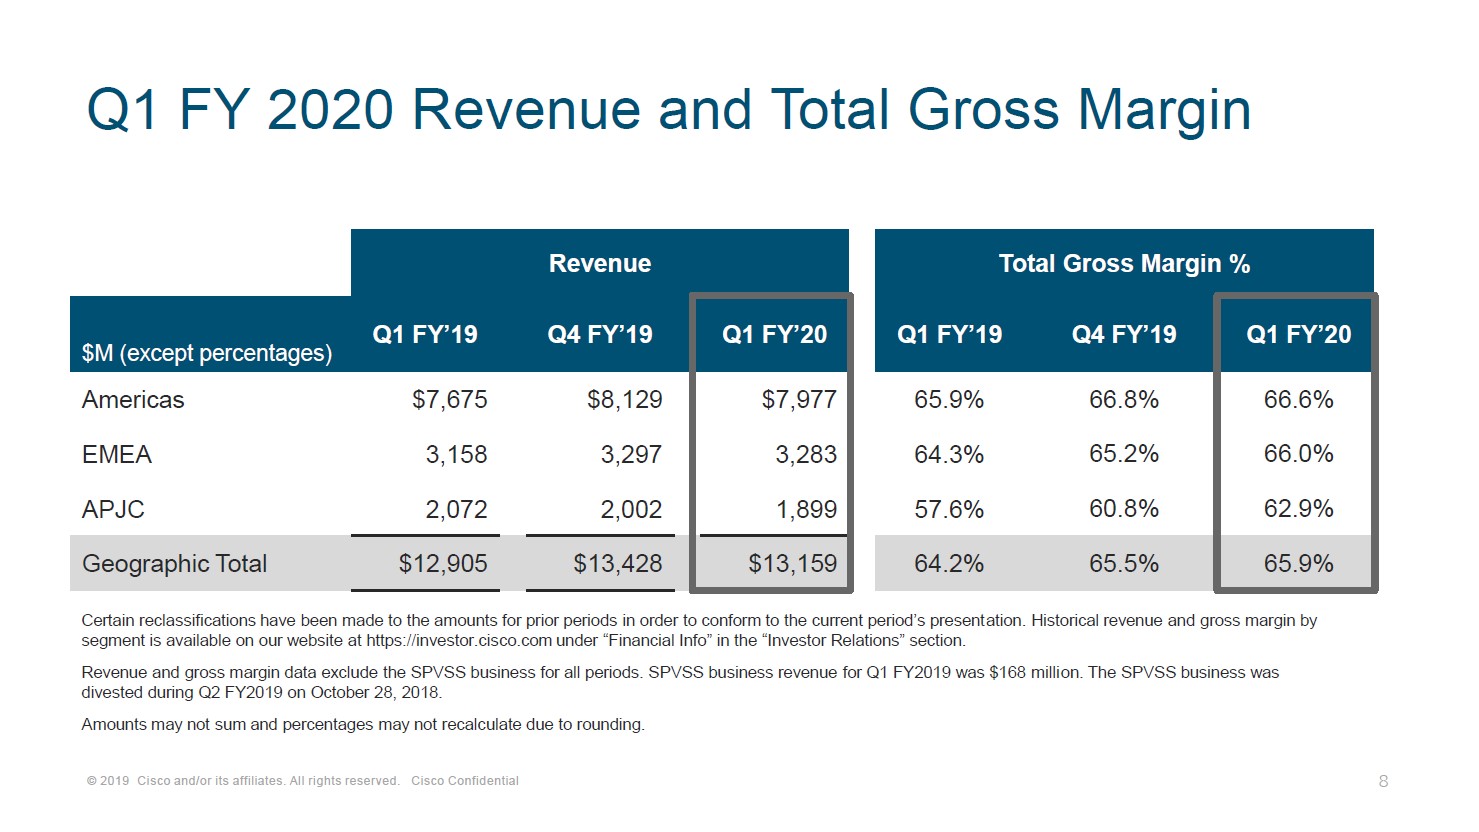
Image Shown: Cisco’s non-GAAP gross margins held up quite well last quarter. Image Source: Cisco – First Quarter Fiscal 2020 Earnings Presentation
Please note that Cisco’s adjusted non-GAAP ‘Services’ sales grew 4% year-over-year in the first quarter (when excluding sales related to SPVSS), outpacing the adjusted 1% year-over-year growth rate of its non-GAAP ‘Product’ revenues. Sales of its ‘Security’ offerings were up 22% year-over-year last quarter. During prepared remarks for Cisco’s latest earnings report management noted;
“Now let’s turn to Security, which is always at the heart of everything we do. It’s deeply integrated into the fabric of our entire portfolio to help secure our customers’ data and address their modern application and multi-cloud environments. Cybersecurity continues to be a top concern for our customers as they evolve their enterprise architectures to address the challenges of an ever-changing threat environment. We have the most comprehensive integrated cybersecurity platform in the market, designed to enable our customers to securely connect any application running on any cloud and delivered to any device.”
Going forward, Cisco sees its company-wide non-GAAP gross margin dropping sequentially to 64.5%-65.5% in the second quarter of its fiscal 2020 as the expected drop in company-wide sales takes its toll. While that stings, that is still higher than its non-GAAP gross margin in the first quarter of its fiscal 2019 as you can see in the graphic above. Cisco should continue generating sizable free cash flows during these turbulent times, and its dividend coverage remains stellar. Cisco’s Dividend Cushion ratio stands at 2.8x, earning the company an EXCELLENT Dividend Coverage rating and supporting an EXCELLENT Dividend Growth trajectory.
Acquisition in the Works
In July 2019, Cisco announced plans to acquire Acacia Communications Inc (ACIA) for $2.6 billion in cash on a net basis ($70 in cash per share of ACIA). For reference, Acacia is an existing Cisco supplier and is billed as such:
“Acacia designs and manufactures high-speed, optical interconnect technologies that allow webscale companies, service providers, and data center operators to meet the fast-growing consumer demands for data.”
Cisco is acquiring Acacia to bulk up its switching, routing and optical networking portfolio at a time of rising multi-cloud usage worldwide. The deal is expected to close during the first half of Cisco’s fiscal 2020 and can easily be funded with cash on hand. Within its earnings press release, Cisco noted its cash, cash equivalents, and short-term investments balance stood at $28.0 billion at the end of the first quarter of its fiscal 2020. While Cisco carried $4.0 billion in short-term debt and $14.5 billion in long-term debt on the books at the end of its latest quarter, its hefty cash-like balance still allowed for a $9.5 billion net cash position.
Furthermore, Cisco’s very capital expenditure-light business model allowed the company to generate $3.4 billion in free cash flows last quarter ($3.6 billion in net operating cash flow less $0.2 billion in capital expenditures). That easily covered $1.5 billion in dividend payments that quarter, on top of $1.0 billion in total share repurchases (‘repurchases of common stock – repurchase program’ plus ‘shares repurchased for tax withholdings on vesting of restricted stock unit’ less negligible ‘issuances of common stock’).
Concluding Thoughts
We’ll have plenty more to say when Cisco publishes its 10-Q filing covering the first quarter of its fiscal 2020. While near-term headwinds are material, Cisco remains very free cash flow positive, carries a nice net cash balance, and its non-GAAP gross margins were quite resilient last quarter. We continue to like the company in both our Best Ideas Newsletter and Dividend Growth Newsletter portfolios.
Communications Equipment Industry – CSCO FNSR JNPR KN NOK SMCI ZAYO
Related – ACIA
———-
Valuentum members have access to our 16-page stock reports, Valuentum Buying Index ratings, Dividend Cushion ratios, fair value estimates and ranges, dividend reports and more. Not a member? Subscribe today. The first 14 days are free.
Callum Turcan does not own shares in any of the securities mentioned above. Cisco Systems Inc (CSCO) is included in Valuentum’s simulated Best Ideas Newsletter and Dividend Growth Newsletter portfolios. Some of the other companies written about in this article may be included in Valuentum’s simulated newsletter portfolios. Contact Valuentum for more information about its editorial policies.