Image Source: GM third-quarter earnings presentation
Despite challenges in its cost structure and the Chinese market, simulated newsletter portfolio idea General Motors turned in a strong third quarter report, and shares reacted favorably after several months of selling pressure. Rival Ford also reported a solid third quarter report, but it no longer expects to hit its 2020 EBIT margin and ROIC targets.
By Kris Rosemann
Shares of simulated newsletter portfolio idea General Motors (GM) leapt during the October 31 trading session after the company released a strong earnings report before the open that included record third-quarter adjusted diluted earnings per share and record third-quarter equity performance from GM China. Net revenue in the period advanced 6.4% on a year-over-year basis to $35.8 billion, and adjusted diluted earnings per share of $1.87 was nearly 42% higher than that of the year-ago period.
GM North America delivered an EBIT-adjusted margin of 10.2%, which was notably higher than the 9.4% mark in the second quarter of 2018 and 8.3% in the year-ago period, thanks to all-new full-size trucks, ongoing crossover performance, and all-around favorable pricing, but management continues to take a cautious tone as it must work to mitigate rising commodity costs. It expects fourth quarter EBIT-adjusted margin to be near the high end of its 9%-10% guidance for the full-year 2018.
GM China delivered record third-quarter equity income of $0.5 billion thanks to improved mix and ongoing focus on cost and productivity improvements, and the business is in the process of introducing ten new or refreshed models in the second half of this year. Such performance was especially notable given the industry-wide weakness seen of late in China, but management points to the company’s growing strength in luxury and premium segments, which are growing in popularity among Chinese consumers, as keys to its success in the quarter. More positive news out of the country recently came via a report that the nation is considering reducing its sales tax on new cars by 50% to stimulate demand. Currency headwinds in South America continue to provide a drag on GM International’s overall results, but the company is quick to note that it has lowered its breakeven point by 40% in the past few years via structural cost initiatives.
We continue to be fans of GM’s income generating potential for shareholders, and management reiterated its full-year 2018 guidance for automotive free cash flow to be roughly $4 billion before the impact of pre-funding non-US pension contributions. Through the first three quarters of 2018, traditional free cash flow came in at nearly $2.7 billion, easily covering cash dividends paid in the period of just under $1.7 billion. The company’s adjusted Dividend Cushion ratio, which mitigates the impact of debt related to GM Financial, currently sits at 3.1 (its unadjusted Dividend Cushion ratio is 1.15), and shares yield ~4.1% as of this writing.
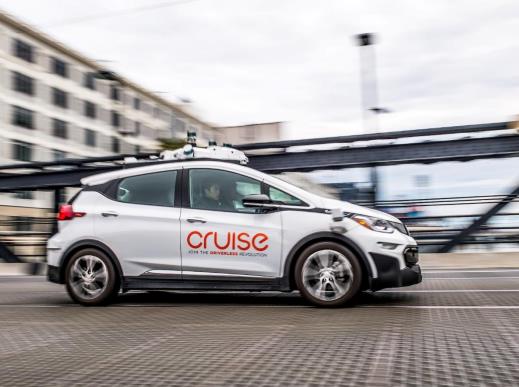
In addition to reiterating its automotive free cash flow guidance, management reiterated its expectations for $2 billion in equity income from GM China and now expects its full-year earnings per share to be at the top of its previously-issued guidance, which was reduced to ~$6.00 from the mid-$6.00 range after the second quarter. We continue to like what we see from GM Cruise, including a partnership with Honda (HMC) to develop a new autonomous vehicle, and management values the business at $14.6 billion as it has now attracted $5 billion in external capital. The company also has plans to increase Bolt EV production by 20% in the fourth quarter of 2018 to meet rising electronic vehicle demand in the evolving auto market, and it has partnered with Delta Electronics to deliver a vehicle capable of a 180-mile driving range with less than 10 minutes of charging.
We believe GM will be at the forefront of the auto revolution as we march towards increasing penetration of electric vehicles and ultimately autonomous vehicles, and major partnerships with the likes of Honda and SoftBank (SFTBY) support such a notion. GM Cruise is targeting commercialization in 2019 in a dense urban environment, and the $2.75 billion contribution from Honda over the span of the next 12 years ($750 million up front) will only boost its prospects. We currently value shares of General Motors at $56 each.
Ford Pulls 2020 EBIT Margin and ROIC Targets
Shares of rival Detroit automaker Ford (F) have also performed nicely since its third quarter report October 24, which revealed strength in its North American business. Revenue advanced 3% on a year-over-year basis in the quarter, but net income and adjusted EBIT both fell from the year-ago period due in large part to ongoing challenges in China. A favorable mix of higher margin products and high-end trim levels in North America were key in driving top-line growth and its 8.8% EBIT margin in North America in the quarter, which was flat compared to the year-ago period as commodity costs provided a headwind.
Management reiterated its 2018 guidance for adjusted earnings per share in a range of $1.30-$1.50 and positive cash flow below that of 2017, but higher costs, uncertainty surrounding the auto industry as a whole, and deterioration in its Europe and China businesses in 2018 will combine to keep it from achieving its previously announced targets of an 8% EBIT margin and high-teens ROIC by 2020. We continue to prefer GM over Ford for a number of reasons, not the least of which is its decisions to mitigate its exposure to less favorable international markets and drive margins higher, especially in the important North American market. Ford’s adjusted Dividend Cushion ratio currently sits at 1.3, and shares yield ~6.3%.
We also prefer GM over Ford due to the former’s budding prospects in next-generation vehicle technology. High-level partnerships may prove to be increasingly important as we move forward in the transition to new auto technology, and GM appears to have a notable leg up in this regard, though we are monitoring recent developments tying Ford to potential partnerships with Chinese Internet giant Baidu (BIDU) and Volkswagen (VWAGY). We currently value shares of Ford at $13 each.
Auto Manufacturers: F, GM, HMC, HOG, TM, TSLA
—–
Valuentum members have access to our 16-page stock reports, Valuentum Buying Index ratings, Dividend Cushion ratios, fair value estimates and ranges, dividend reports and more. Not a member? Subscribe today. The first 14 days are free.
Kris Rosemann does not own shares in any of the securities mentioned above. Some of the companies written about in this article may be included in Valuentum’s simulated newsletter portfolios. Contact Valuentum for more information about its editorial policies.