Tiffany’s first-quarter 2018 results were from another planet! Strong increases in comparable store sales almost across the board, blowing by consensus estimates, and the company’s free cash flow outlook has only improved. The read-through is significantly positive for aspirational and luxury players, in our view, and Ralph Lauren’s gross-margin improvement during its quarterly release bodes well for many brands across most of the high-end apparel space. Foreign tourism and high-end consumer spending remain very strong on the basis of Tiffany’s quarterly results, and geopolitical concerns did not impact the breakneck pace of jewelry sales in China or the Korean Peninsula. It’s hard to imagine Tiffany having a better first quarter than it did.
By Brian Nelson, CFA
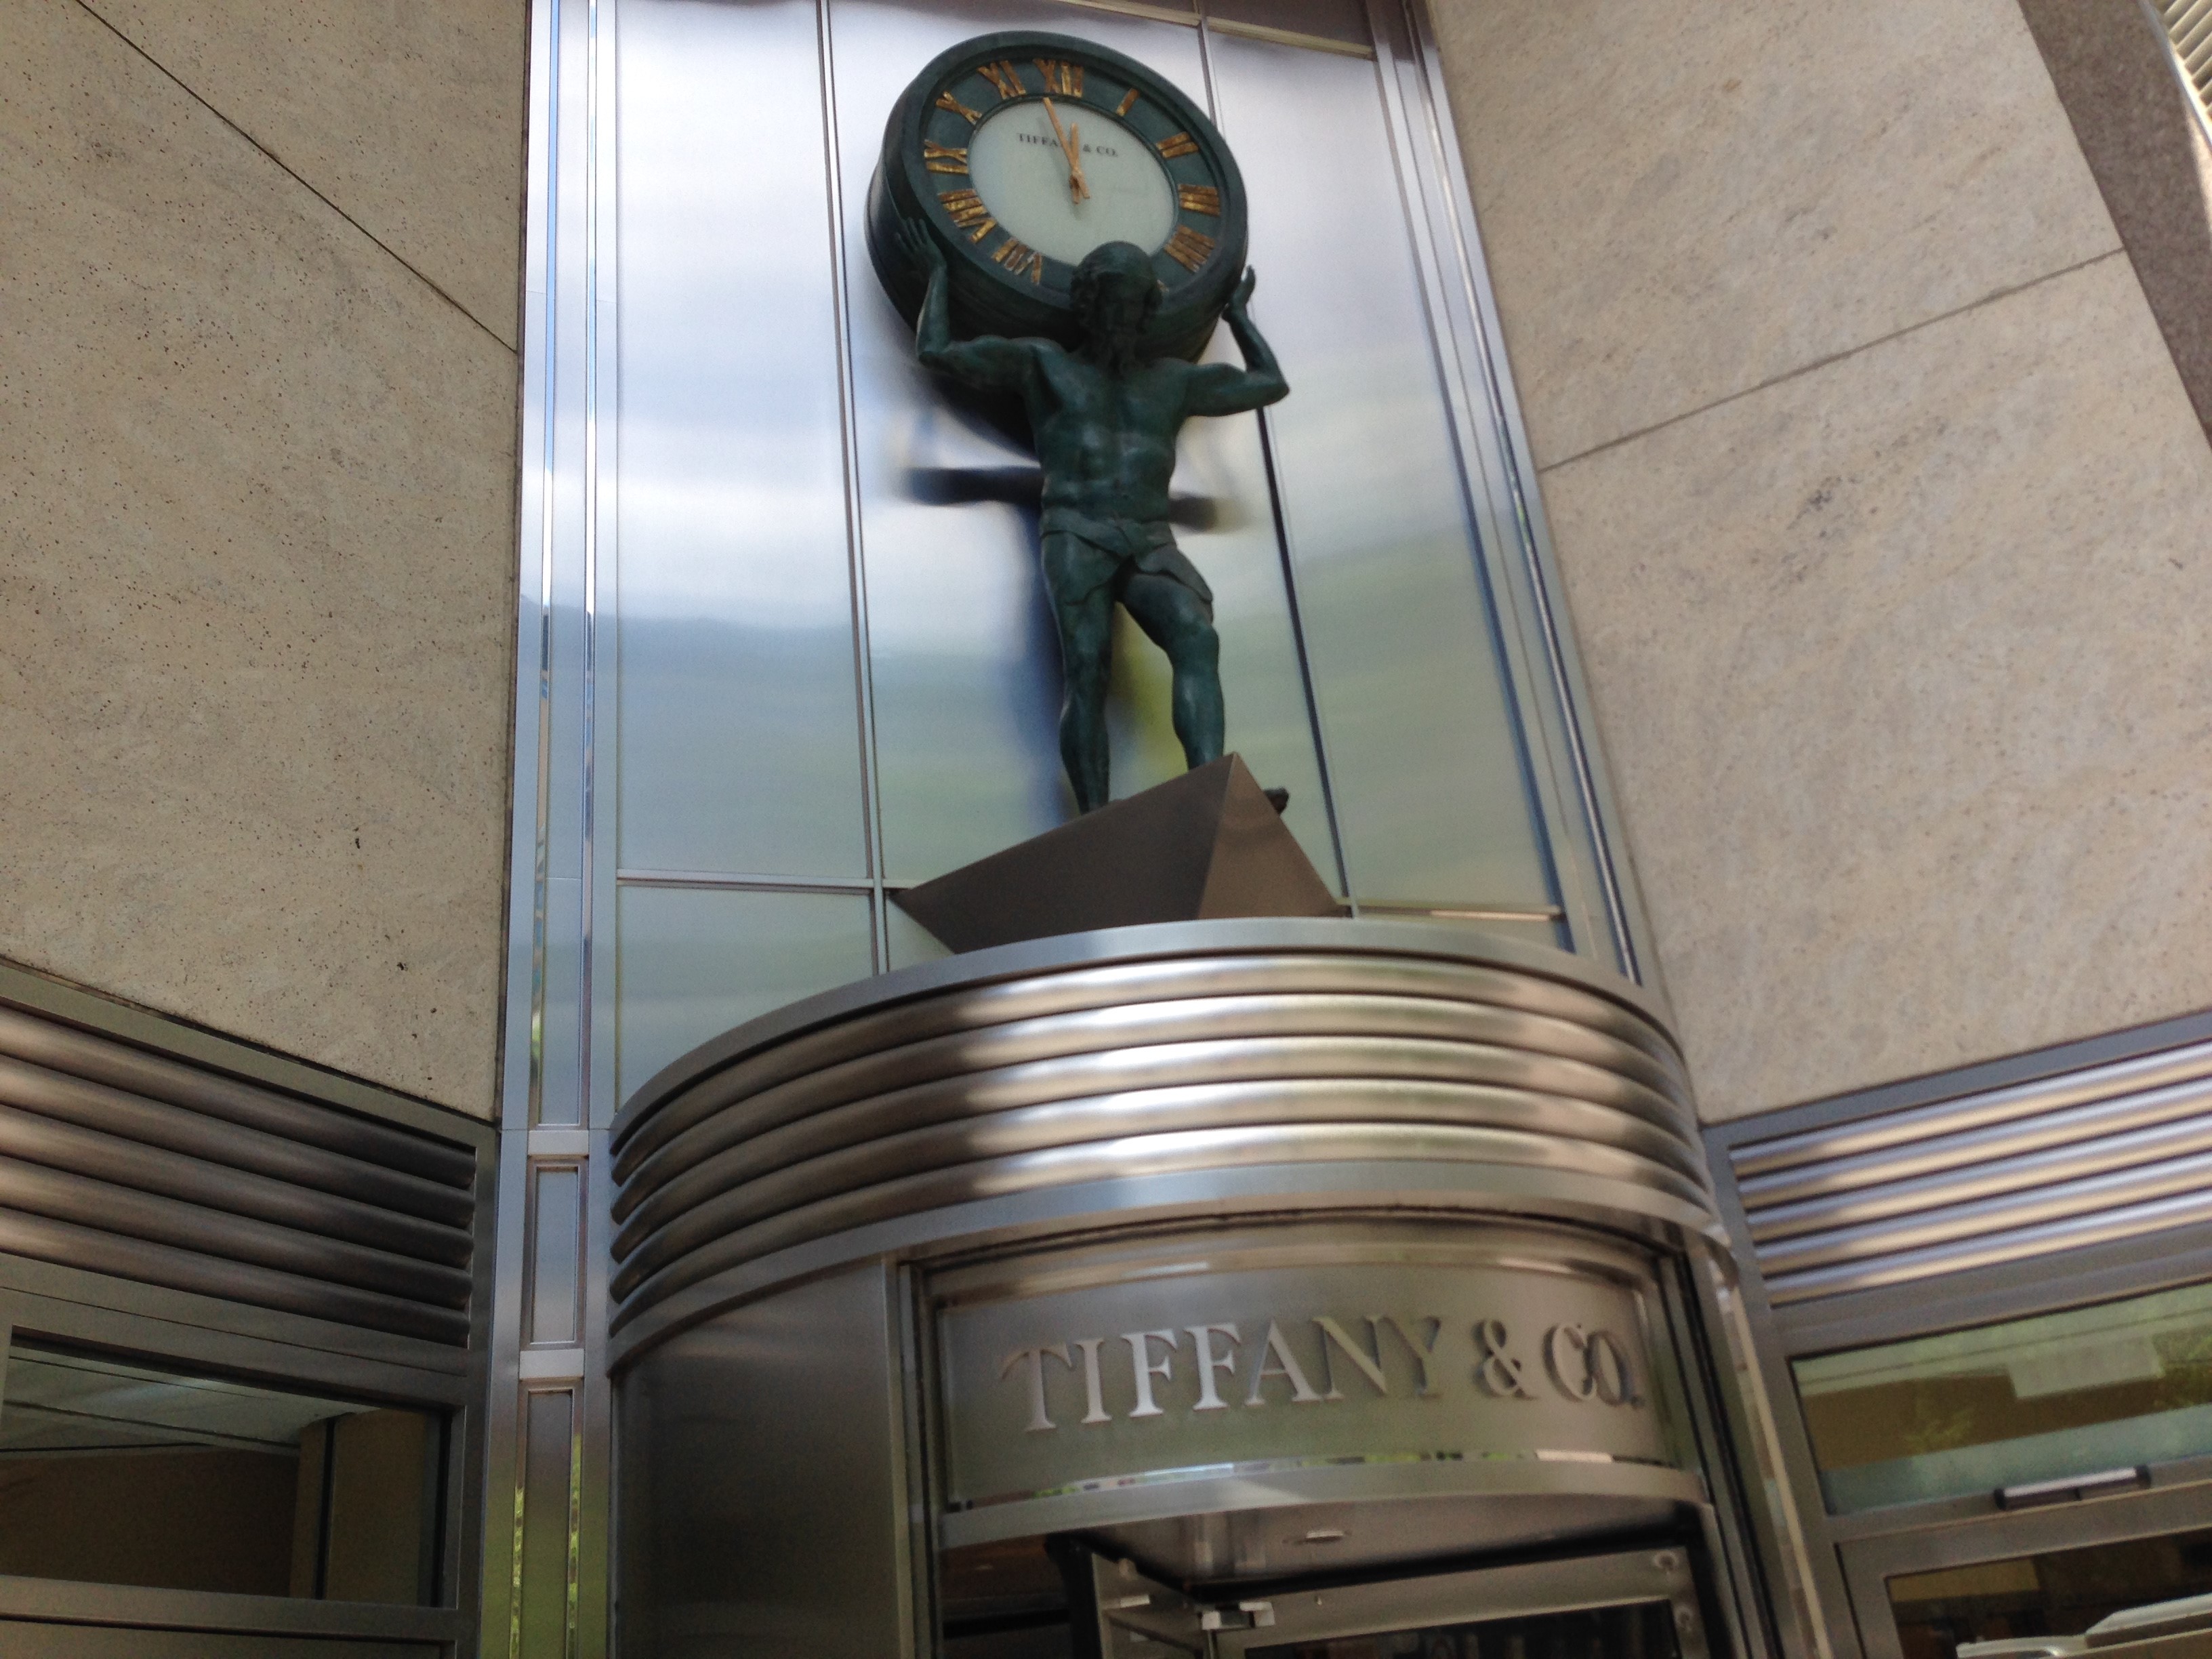
On May 23, high-end jewelry retailer Tiffany (TIF), known best for its little blue boxes and the excitement they bring, reported fantastic first-quarter 2018 results that sent shares soaring. Worldwide net sales leapt an impressive 15% during the quarter, while a higher operating margin and lower tax bill combined to drive net earnings more than 50% higher than the same period a year ago. The top-line expansion in the quarter was mostly organic, too, with comparable store sales leaping a robust 10% (consensus was expecting only 2.6% comparable store sales growth). On a per-share basis, net earnings jumped to $1.14 from $0.74 in last year’s quarter.
The numbers were so good that Tiffany wasted no time upping its full-year guidance. The company now expects worldwide net sales to increase by a high-single-digit percentage over the prior year (was mid-single-digits) and net earnings to come in the range of $4.50-$4.70 per diluted share (was $4.25-$4.45). Mid-to-high single-digit comparable store sales growth is now expected during 2018 (was low-to-mid single-digits), though the company’s operating margin will still face some pressure due to higher SG&A expense growth (no change to expectations). Net cash from operating activities is now expected to come in at ~$700 million for the full year (was $660 million) and free cash flow to be higher than $400 million (was $380 million), on capital spending of ~$280 million (no change to expectations).
Tiffany’s brand remains as strong as ever, and the company’s efforts to drive comparable store sales higher are bearing fruit. Ongoing renewal of product offerings and enhanced in-store presentation are driving sales conversations, and the company is delivering on its omnichannel customer experience, with ongoing investments in its website and with Farfetch, an online fashion retail platform, among others. Tiffany is not resting on the strong report and the higher SG&A spend will be focused on amplifying its brand message. Its latest jewelry collection in platinum and diamonds, PAPER FLOWERS, is one catalyst, and the company’s new marketing campaign, “Believe in Dreams,” has only just debuted, while its “Believe in Love” campaign drove engagement jewelry sales up 11% in the period. We think the company’s latest efforts are off to a good start given how optimistic management is about the balance of the year.
On a geographic basis, total sales in the Americas region advanced 9%, but while this was a solid number, growth in other regions of the world was much more impressive. Importantly, total net sales in the Asia-Pacific region increased 28% as the company benefited from strength in China (a “strong rebound” in Hong Kong) and Korea. Comparable store sales in its Asia-Pacific region were up 14% in the period. In Japan, total net sales leapt 17% thanks to comparable store sales growth of 14%, while total net sales in Europe increased 13% thanks mostly to currency impacts as comparable store sales growth was modest at 2%. Given all the talk of trade wars between the US and China, and ongoing unrest on the Korean Peninsula, Tiffany’s Asia-Pacific growth numbers were a welcome showing, if not an extremely impressive one.
We expect to raise our fair value estimate of Tiffany’s equity considerably on what we believe to be improved execution across its geographical segments and a forecast of strength to continue with respect to comparable store sales expansion. We’d be more skeptical in making a fair value adjustment had one geographic region or one line of jewelry account for the expected strength in 2018, for example, but the strength was across the board in the first quarter, pointing to a high degree of sustainability, especially as Tiffany keeps driving marketing spend. Our free cash flow expectations need to be ratcheted higher, too, and we expect to lighten our cost of capital assumption as growth in its Asia-Pacific region seems much more resilient to geopolitical uncertainty than we previously thought. Our updated valuation and dividend report on Tiffany will be uploaded shortly, and we expect the fair value estimate increase to be material.
As we look for read-throughs on Tiffany’s first-quarter 2018 results, we think the quarterly performance speaks loudly to the resiliency of global consumer spending in the aspirational and luxury segments across the globe, and even points to strength with respect to foreign tourism and travel, a net positive for the travel-related entities, including simulated Best Ideas Newsletter idea Booking (BKNG), formerly called Priceline. Our latest 9-10 on the Valuentum Buying Index (aside from the current idea Facebook), Michael Kors (KORS) is getting a boost on the news, as is former simulated Dividend Growth Newsletter idea Tapesty (TPR), formerly known as Coach. We would expect some overlap with Tiffany’s customer base with the aspirational players, so fundamentally, this is a positive read-through, too, for entities such as Signet (SIG), which recently had a major setback late last year.
Similar to the nice margin expansion–but perhaps unsustainable due to expectations for increased marketing spend–in Tiffany’s first-quarter 2018 numbers, Ralph Lauren (RL) showcased significant profitability expansion, too, when it released its fiscal fourth-quarter results May 23. Unlike at Tiffany, however, revenue at Ralph Lauren faced meaningful pressure in the period (down 7% on a constant-currency basis), and the premium lifestyle product retailer still expects net sales to decline at a low-single-digit pace during fiscal 2019 (the upcoming four quarters). However, what has the market excited is that Ralph Lauren’s adjusted gross margin increased 440 basis during its fiscal fourth quarter, perhaps suggesting that consumers continue to be willing not only to spend, but to spend up (“full price”). Such a trend is a positive development for margins across most of the apparel retail industry, perhaps boding particularly well for other higher-end brands, including PVH (PVH), Lululemon (LULU), and even Nike (NKE).
We’ll be fine-tuning our models for many of the high-end retailers on the news.
Luxury Goods – Established Brands: AVP, EL, LULU, NKE, PHG, PVH, REV, SIG, SNE, UA, VFC
Luxury Goods – Ultra & Aspirational: BID, CFRUY, FOSL, KORS, LVMHF, RL, TIF, TPR
Related: FXI, MCHI, EWJ, EWY, WSM, ROST, TJX, LB, URBN
—–
Valuentum members have access to our 16-page stock reports, Valuentum Buying Index ratings, Dividend Cushion ratios, fair value estimates and ranges, dividend reports and more. Not a member? Subscribe today. The first 14 days are free.
Brian Nelson does not own shares in any of the securities mentioned above. Some of the companies written about in this article may be included in Valuentum’s simulated newsletter portfolios. Contact Valuentum for more information about its editorial policies.