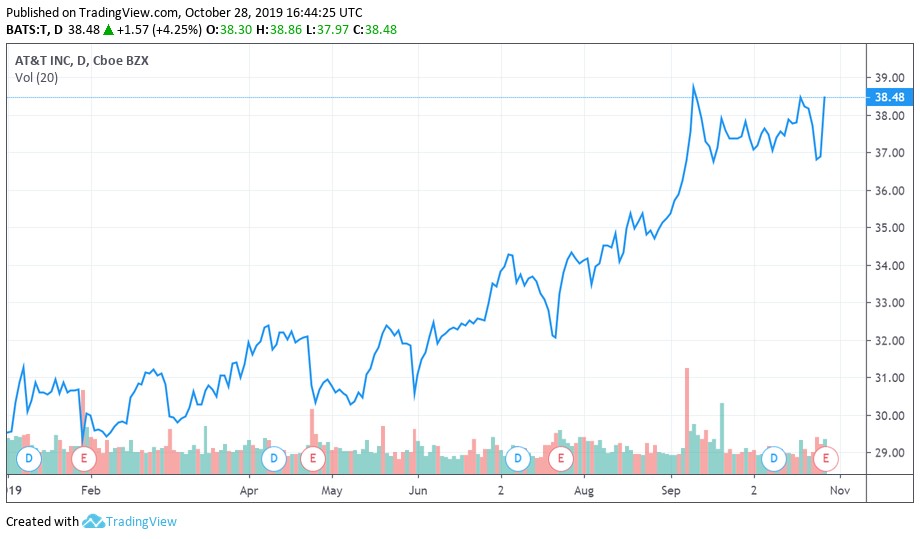
Image Shown: AT&T continues to surge higher this year as shares of T converge towards their intrinsic value, a process supported by recent activist investor activity directed towards the company.
If you may wish to add the High Yield Dividend Newsletter to your membership, please click here.
By Callum Turcan and Brian Nelson, CFA
AT&T
On October 28, AT&T Inc (T) reported third-quarter 2019 earnings, and the market clearly liked what the company had to say. Shares of AT&T are trading up ~4% as of this writing as the company’s stock price continues converging towards its intrinsic value, in our view. Our fair value estimate for AT&T stands at $40 per share, with room for upside, and we continue to like the firm in our High Yield Dividend Newsletter portfolio. Shares of T yield 5.3% as of this writing.
In 2020, AT&T is targeting 1%-2% revenue growth, adjusted (non-GAAP) EPS of $3.60-$3.70, a flat adjusted EBITDA margin with 2019 levels, around $28.0 billion in free cash flows, a dividend payout ratio as a percentage of free cash flows in the low-50% range, and $5.0-$10.0 billion in asset monetization. Some quick notes on this outlook: top line growth will likely pick up pace as the coming 5G rollout gets underway (with mass consumer adoption in the US representing a 2020s story), free cash flows are expected to remain rock solid next year, and AT&T will retain enough “excess” free cash flow (free cash flow less dividend payments) to continue moving forward with meaningful deleveraging activities.
The telecommunications and media entertainment juggernaut has already begun to pursue meaningful divestments. AT&T very recently agreed to sell its majority equity stake in Central European Media Enterprises Ltd. (CETV) for $1.1 billion, its wireless and wireline operations in Puerto Rico and US Virgin Islands for $1.95 billion, and management wants to communicate that more deals are on the way. These proceeds will go towards debt reduction and share buybacks, especially if activist investor Elliott Management gets its way. As things stand today, AT&T has committed to using 50%-70% of its excess free cash flows to repurchasing shares, with the goal being to retire ~70% of the shares issued to fund its purchase of Time Warner.
By 2022, AT&T is targeting $30.0-$32.0 billion in free cash flow, which will be accompanied by modest dividend growth, with management seeking to lower the firm’s dividend payout ratio (as a percentage of free cash flows) below 50% during this period. Deleveraging activities will help drive down AT&T’s net-debt-to-adjusted-EBITDA ratio to 2.00x-2.25x by 2022. Net-debt-to-adjusted_EBITDA stood at 2.66x at the end of the third quarter of 2019, indicating there’s plenty of room to go on this front.
Revenue growth is expected at 1%-2% CAGR through 2022, with adjusted (non-GAAP) EPS expected to grow to $4.50-$4.80 by 2022. We like AT&T’s focus on improving its profitability metrics, with management targeting a 200 basis point expansion in the company’s adjusted EBITDA margin through 2022, which is expected to hit 35%. Cost rationalizations combined with the launch of its new streaming service HBO Max will likely play key roles here.
To better stick with its current strategy, AT&T announced it would consider one potential new director at its next board meeting and another new potential director in 2020. Furthermore, the company committed to not pursue any more major acquisitions over the next few years. We liked what we saw in AT&T’s latest earnings report and think the market is beginning to seriously take note.
Philip Morris International
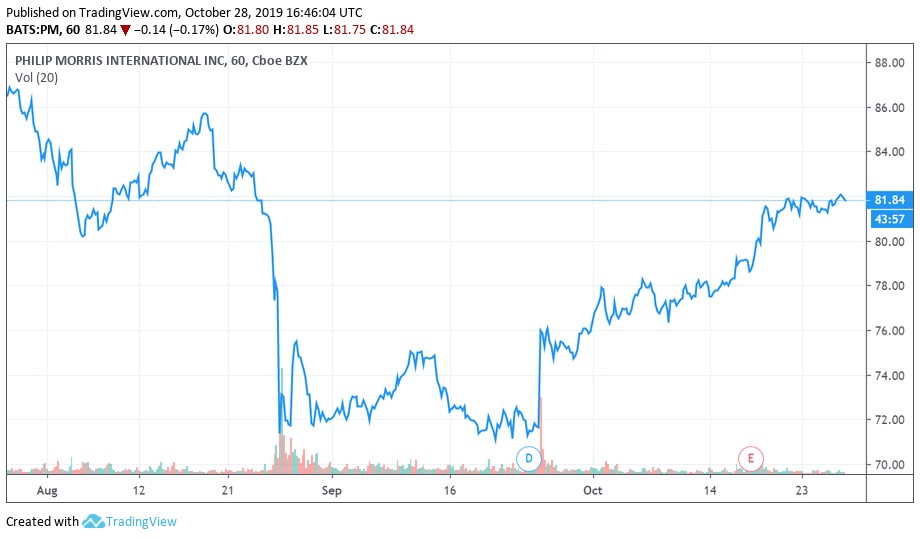
Image Shown: Shares of Philip Morris International are recovering after fears over its potential merger with Altria Group faded away when it became clear no such deal would materialize. The market was primarily worried about the terms Philip Morris International might agree to regarding the potential pro forma ownership for each firm’s shareholder base, and not the underlying reasoning behind the tie-up itself.
Back on October 18, we covered Philip Morris International Inc’s (PM) third-quarter 2019 earnings report that was published a day earlier (article link here). Since then, shares of PM have only continued to climb higher, and we see that as a sign investors are beginning to factor in the company’s stellar free cash flow profile. Philip Morris International is included in our High Yield Dividend Newsletter portfolio. Shares of PM yield 5.7% as of this writing.
As an aside, the recent controversies regarding vaping in the US and more specifically, Juul Labs, may work in Philip Morris International’s favor. Its own alternative smoking products are markedly different (in taste, heating method, and targeted demographics) than the Juul offering with an eye towards Philip Morris International’s IQOS offering that recently launched in the US. Philip Morris International’s alternative tobacco products and the pricing power of its traditional cigarette brands supports its free cash flow trajectory over the coming years and offers room for upside should IQOS sell well.
When it comes to Philip Morris International’s dividend coverage, while we give the firm a Dividend Cushion ratio of 0.8x, please note we adjusted its Dividend Safety rating to GOOD (from POOR, which is normally what a sub-1.25x Dividend Cushion ratio would earn) and our reasoning is straightforward: The free cash flow profile of Philip Morris International is simply stellar ($6.1 billion in free cash flows during the first three quarters of 2019) which fully covered $5.3 billion in dividend payments during this period, and furthermore, the company does not allocate a meaningful amount of its free cash flows towards share repurchases. Total debt of $31.8 billion, inclusive of short-term debt, at the end of September 2019 is somewhat offset by $6.5 billion in cash and cash equivalents.
When considering Philip Morris International’s ‘A-rated’ investment grade credit ratings and its strong free cash flow profile, we see that debt burden as easily manageable. As a company that sells tobacco products, Philip Morris International is somewhat insulated from a slowdown in global economic activity as its products have relatively inelastic demand and tend to be high up on the spending priorities of tobacco consumers. We think Philip Morris International carries solid dividend coverage and should be a major beneficiary of a lower interest rate environment. Our fair value estimate for shares of PM stands at $77, with room to climb higher as the top end of our fair value estimate range sits at $92 per share.
Altria Group Inc (MO) carries a Dividend Cushion ratio of 1.0x, but we assign it a POOR Dividend Safety rating due to concerns regarding the value of its 35% stake in Juul Labs (with US regulators aggressively cracking down on the company) and its ~45% stake in marijuana firm Cronos Group Inc (CRON), which could change should Altria exercise its warrants to buy a larger stake in Cronos. The greater likelihood of future volatility in Altria’s free cash flows, with an eye towards downside risks (stemming from greater regulatory scrutiny of vaping products in particular, and the lack of clarity regarding Cronos’ future free cash flows), represents the main reason why we didn’t adjust Altria’s Dividend Safety rating upwards as we did with Philip Morris International. We continue to like Philip Morris International more than Altria in part for this reason.
Concluding Thoughts
We continue to like the resurgence in AT&T’s shares of late. The company is rapidly converging to our $40 per share fair value estimate, and as the company divests assets and pursues deleveraging, its dividend growth profile is enhanced. Shares already yield an enticing 5.3%, too. Philip Morris has rallied considerably since it broke deal talks with Altria, and we believe the company has a relatively lower business risk profile than Altria. Both Philip Morris and Altria have Dividend Cushion ratios below the 1.25x threshold, or GOOD threshold, but given more positive overall trends at Philip Morris, we prefer the company over Altria at this time. Shares of Philip Morris yield a lofty 5.7% at the time of this writing.
Telecom Services – BCE CTL EQIX FTR S T TMUS VZ VOD
Tobacco Industry – BTI MO PM SWM VGR
Related smoking: IMBBY, JAPAY, GLLA, VAPE
Marijuana stocks: ACB, ACNNF, APHA, CGC, CRON, HEXO, STZ, TLRY
Related ETFs: MJ, YOLO, ACT, THCX, SOIL, CNBS, TOKE, POTX
—-
Valuentum members have access to our 16-page stock reports, Valuentum Buying Index ratings, Dividend Cushion ratios, fair value estimates and ranges, dividend reports and more. Not a member? Subscribe today. The first 14 days are free.
Callum Turcan does not own shares in any of the securities mentioned above. Philip Morris International Inc (PM) and AT&T Inc (T) are both included in Valuentum’s simulated High Yield Dividend Newsletter portfolio. Some of the other companies written about in this article may be included in Valuentum’s simulated newsletter portfolios. Contact Valuentum for more information about its editorial policies.